If you want to save some money, you need to know that there are many tax breaks for retirees that are always overlooked. This is an easy way to put a little bit more money into your accounts, so why not take advantage of it?
However, it is not a breeze to take care of your money during retirement, and this is why many times people totally forget about the money they can get from tax savings. You should closely observe your tax situation, and when you can, try to save some cash.
Read on and learn all you need to know about the most overlooked tax breaks for retirees. Learn to make the most out of your retirement!
1. Medicare tax deduction
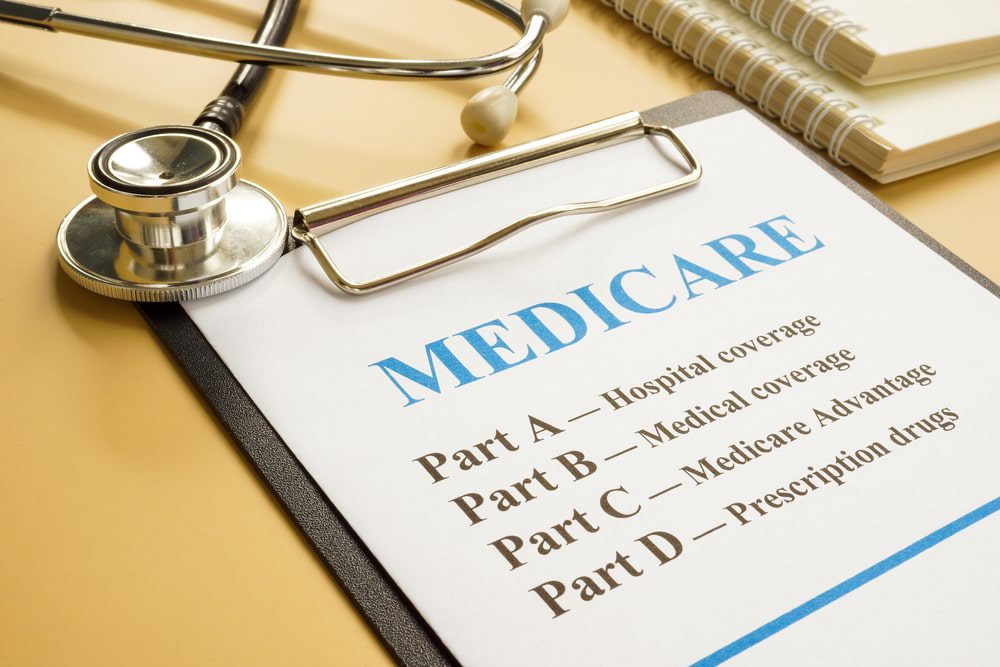
We all know about Medicare, and we are also grateful for its existence. This national insurance plan is literally saving the lives of many seniors, but did you know that you can get tax deductions for it?
If you decide to work after the age of 65 and are self-employed, you will need to pay premiums for Medicare Part D and Part B. The catch here is that you can deduct the premiums and make some money. Other things that also get deducted are the cost of the Medicare Advantage Plan and Medigap.
This is one of the best tax breaks for retirees, and we believe that it can help you a lot to be aware of it. Even more, whether you itemize or not, you will still be able to deduct these expenses.
However, you still need to keep in mind that if your spouse’s employer offers them a health plan and you are also covered by it, you will not be able to deduct the Medicare taxes.

2. The RMD
Speaking about the world of taxes, you’ve probably heard about the RMD, also known as required minimum distributions. It is everywhere, and everyone talks about it. But this is not something random. RMDs are important, and they can offer you one of the best tax breaks for retirees.
A few years ago, RMDs were no longer required, but now they are here once again, and you should know how to manage them. Fortunately, retirees withdrawing RMDs from conventional IRAs may have an additional option for completing the pay-as-you-go obligation.
Take a moment and think about whether you need the RMDs in order to live on a daily basis. If you have enough money for a comfortable life, you don’t need to withdraw the RMD. You can wait until the end of the year, in December, and you can take the money then.
Request that your IRA sponsor withhold a significant percentage of the distribution for the IRS, sufficient to meet your anticipated tax on both the RMD and additional taxable income.
When you send the checks, it is considered that you have paid the estimated taxes, and you can withdraw all the money at the end of the year without worrying. Keep your IRA for most of the year, and you will still be able to avoid the underpayment penalty. This applies if your RMD is enough to cover all the tax bills.

3. IRA contribution from your spouse
If you retire, this doesn’t mean that you will no longer be able to put some money into an IRA. Usually, the rule that allows you to put money into an IRA says that you need to have earned income, but if you have a spouse who is still working, this will make them able to put money into their IRA.
They can usually deposit up to $6,500 into a regular or Roth IRA you already possess. The 2024 IRA contribution maximum is raised to $7,000. You are eligible for this one of the tax breaks for retirees if your spouse earns enough to support your contribution (as well as any contributions to his or her account).
However, there is one essential constraint to be aware of. If just one of you is 50 or older, the total of your contributions to your Individual Retirement Account and your spouse’s IRA are limited to $13,000 for the 2023 tax year. If you are both over 50 years old, your combined payments cannot exceed $15,000 ($16,000 in 2024).

4. Don’t fall for the pension payout trap
When you have to pay taxes, there is an exception to the rule that allows you to choose from where these taxes will be withheld. It can be from your IRAs, pensions, various other retirement plans, or annuities. If you get a one-time payment or similar rollover payment from your employer’s plan, you may be in danger of falling into a pension payout trap.
When you withdraw money from any of your retirement accounts, the company that keeps them needs to stop the 20% that will go to the IRS. Even if you finish the rollover during the sixty days allowed by law, the Internal Revenue Service (IRS) will keep the 20% up until you file your year-end tax return and demand your refund.
What makes it even more difficult is how you may roll more than one hundred percent of the single payment if the IRS keeps 20%. Failure to contribute the additional funds to the IRA would result in a taxed distribution. As a result, you’d face a sudden tax obligation and have less money in your IRA.
But if you want to take advantage of one of the best tax breaks for retirees and avoid something like that happening, you need to know that there is a solution. What you should do is ask your employer to send the money to the rollover IRA directly.
Even if you are interested in using part of the money as soon as possible, your best strategy is to have your employer arrange the direct IRA transfer. Then, when you take cash from the IRA, you decide whether or not to withhold taxes.
5. Tax credit
If you are part of the low-income older adults group, you might be eligible to take a tax credit. This is another one of the tax breaks for retirees that might help you. To qualify, you need to meet one of the next criteria at the end of the tax year: you are 65 or older or you retired when you were under 65 because of a total disability or a permanent one, your disability income is taxed.
The first income test is based on the adjusted gross income. If you submit your tax return as a single, head-of-household, or qualified widow(er), your adjusted gross income must be less than $17,500. If you are married and, as a result, file for a joint return and only one of the spouses is eligible for the credit, you need to make sure that your AGI is less than $20,000. Also, if both spouses qualify, make sure the AIG is less than $25,000.
The second income test is calculated on your total nontaxable Social Security, disability income, annuity, and pension. Single, head-of-household, and qualified widow(er) taxpayers’ cumulative earnings have to be under five thousand dollars. If one spouse is eligible for the credit, the same limit for AIG applies. If both qualify, the limit is $7,500.
Something that might help you keep track of your budget is a Clever Fox Budget Planner.
You should also read 10 Affordable Online Shopping Websites That Will Save You Money