Retiree healthcare costs are shifting significantly as federal legislation reshapes prescription pricing and base coverage rates. Understanding these upcoming adjustments today will protect your retirement budget from unexpected out-of-pocket expenses next year.
Between higher baseline deductibles and new drug price limits, your monthly medical bills will look very different. The 2027 landscape brings both welcome cost caps and rising base premiums across primary coverage parts.
Preparing for these changes now lets you adjust your savings and choose the best plan during open enrollment. Here are the ten specific Medicare costs you must track to keep your healthcare spending secure.
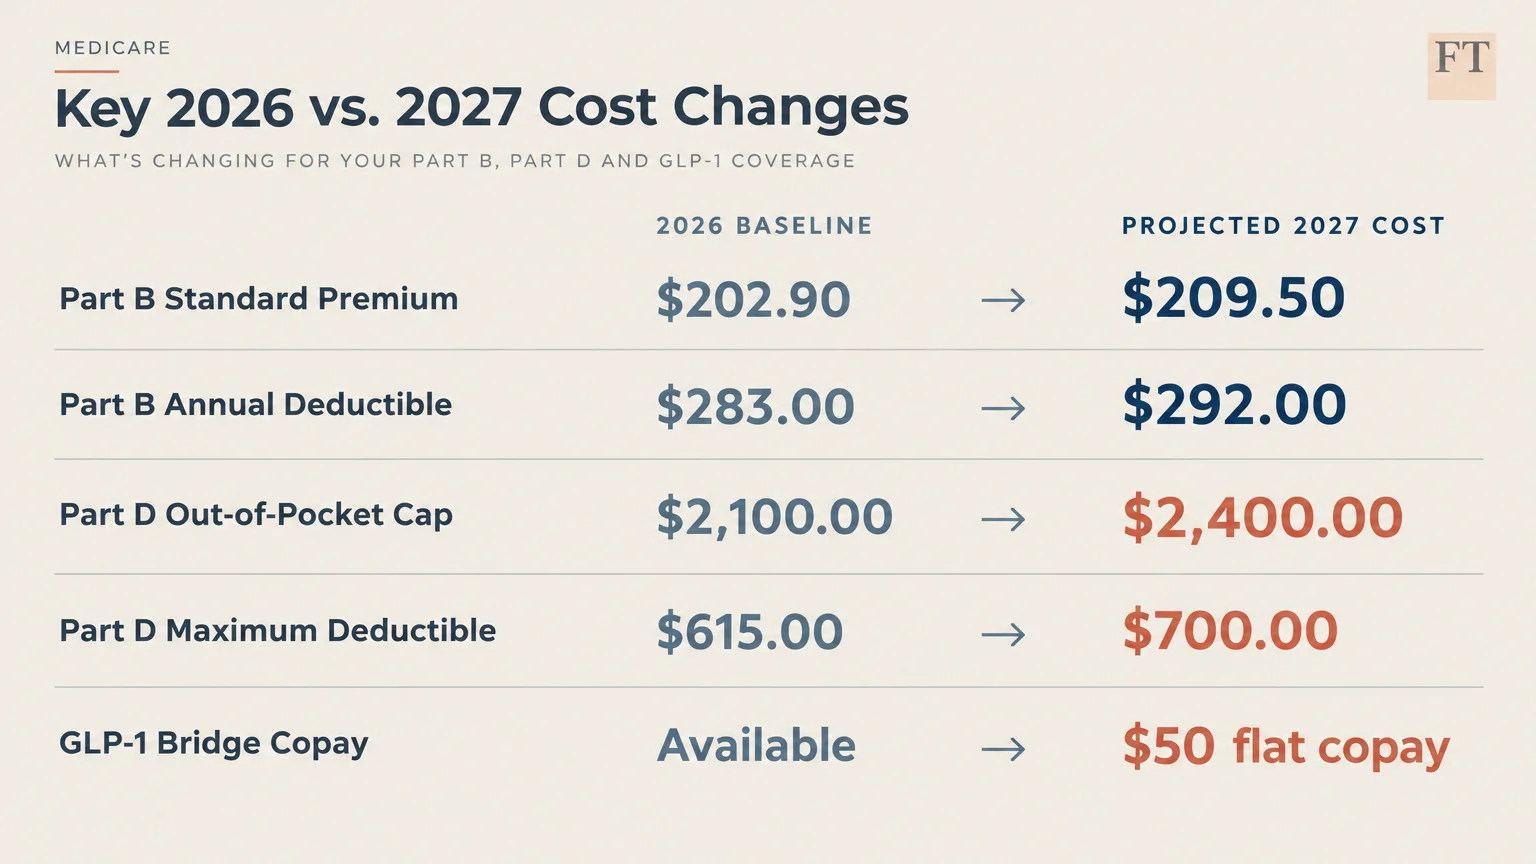
At a Glance: Key Medicare Changes for 2027
Preparing your retirement budget requires tracking both premiums and out-of-pocket maximums. This summary highlights the key cost projections you will navigate in 2027.
| Cost Category | 2026 Baseline | Projected 2027 Cost | Budget Impact |
|---|---|---|---|
| Part B Standard Monthly Premium | $202.90 | $209.50 | Base monthly expense rises by $6.60 |
| Part B Annual Deductible | $283.00 | $292.00 | $9 increase before 80/20 coinsurance begins |
| Part D Out-of-Pocket Cap | $2,100.00 | $2,400.00 | Hard annual maximum on covered medications |
| Part D Maximum Deductible | $615.00 | $700.00 | Up to $85 higher upfront prescription deductible |
| GLP-1 Bridge Copay Program | Available | $50 flat copay | Predictable pricing for qualifying therapies |
1. Higher Standard Part B Monthly Premiums
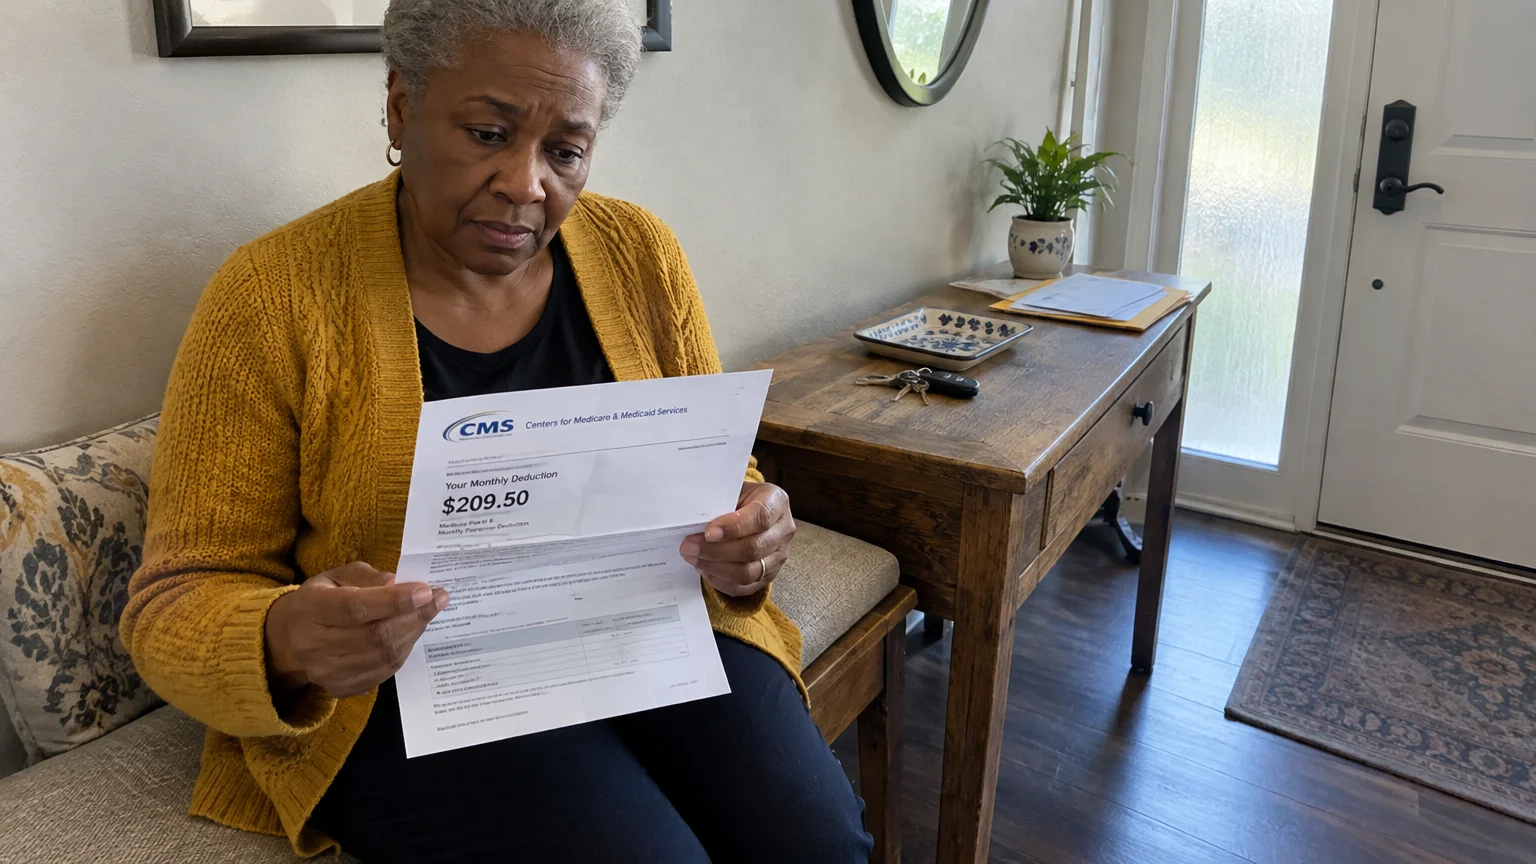
According to the Medicare Board of Trustees Report, your standard monthly Part B premium is projected to reach $209.50 in 2027. This represents a $6.60 increase from the $202.90 rate set for 2026.
The Centers for Medicare & Medicaid Services (CMS) finalizes these premium numbers each November. Most retirees have this amount deducted automatically from their monthly Social Security check.
Fortunately, the statutory hold-harmless provision shields approximately 70% of enrollees. This rule ensures that premium hikes cannot reduce your net monthly Social Security benefit below the previous year’s level.
2. An Increased Part B Annual Outpatient Deductible
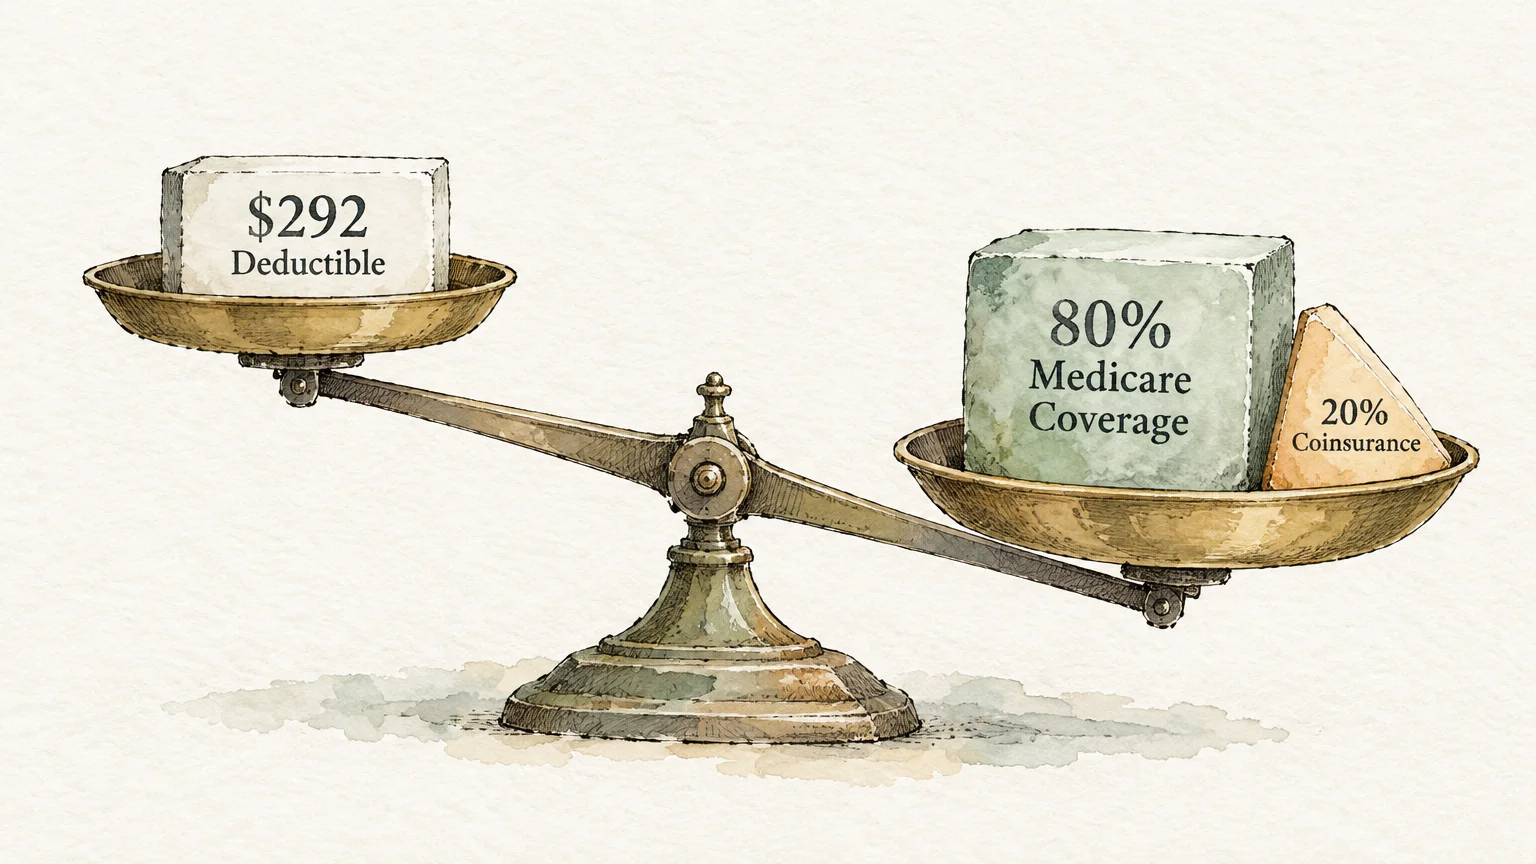
Before Medicare begins paying its standard 80% share for outpatient visits, you must satisfy the annual Part B deductible. Projections show this deductible rising by $9 to reach $292 in 2027.
This outpatient deductible applies to doctor visits, diagnostic lab tests, and physical therapy sessions. Once you meet this threshold, your supplemental policy or secondary insurance helps pay the remaining 20% coinsurance.
3. The $2,400 Part D Out-of-Pocket Spending Cap
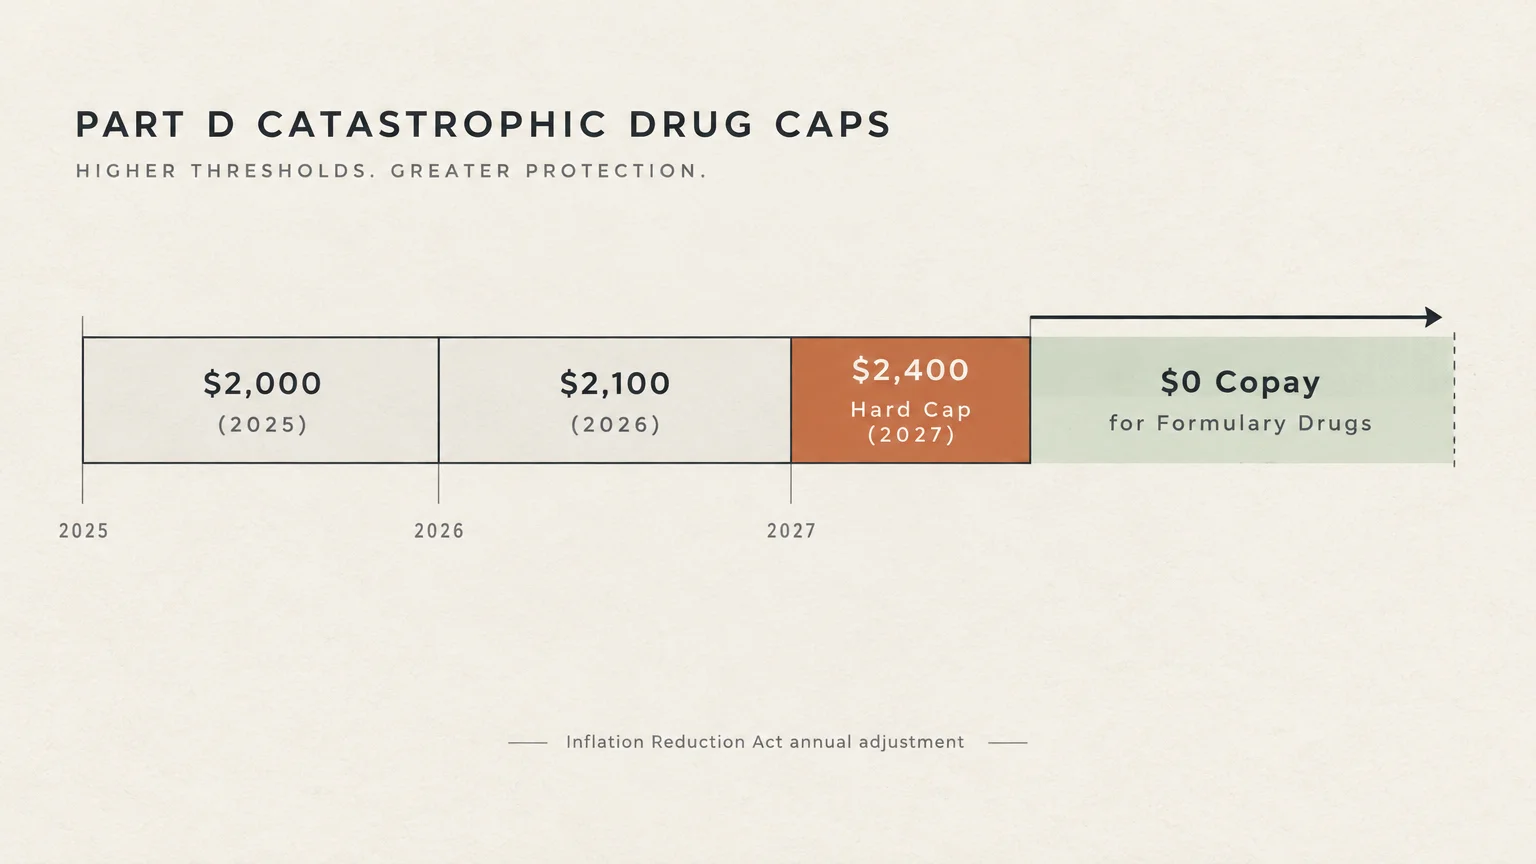
The Inflation Reduction Act established a protective spending limit on prescription medications. For 2027, your maximum out-of-pocket spending cap on covered Part D medications rises to $2,400.
This represents an adjustment from the $2,100 limit in 2026 and the original $2,000 threshold from 2025. Once your qualifying pharmacy spending hits this cap, you pay $0 for formulary drugs for the rest of the calendar year.
This hard cap offers critical peace of mind if you manage chronic illnesses requiring specialty medications. It eliminates the catastrophic coverage phase that previously exposed retirees to unlimited pharmacy copayments.
4. Rising Maximum Part D Prescription Deductibles
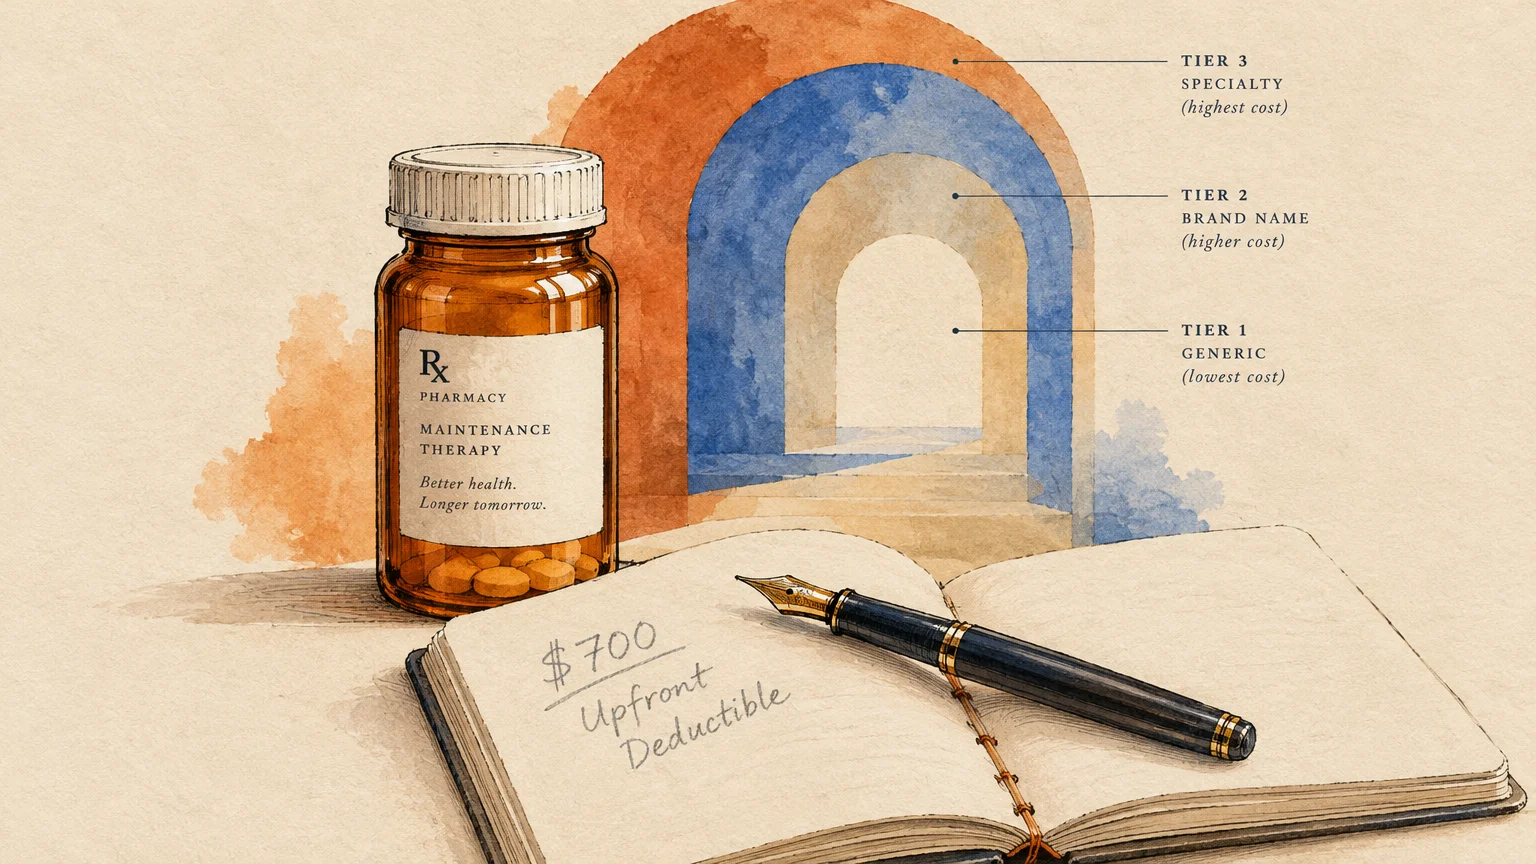
While the annual cap protects heavy prescription users, the upfront deductible is growing. CMS finalized the maximum allowable Part D deductible at $700 for 2027, an increase from $615 in 2026.
Private insurance carriers can set their deductibles lower, but many plans adopt this statutory ceiling. You must pay this full amount out of pocket before your copayments or coinsurance tiers take effect.
Review your annual drug usage carefully during fall enrollment. Choosing a plan with a lower deductible often saves money if you take multiple generic maintenance drugs throughout the year.
5. Drug Price Relief Under IRA Round 2 Negotiations
Starting January 1, 2027, Medicare implements newly negotiated Maximum Fair Prices for 15 high-cost Part D drugs. This second round follows the initial ten medications discounted under federal reform in 2026.
The updated list includes widely prescribed therapies such as Ozempic, Rybelsus, and Wegovy. CMS estimates this round will save Part D enrollees roughly $685 million in direct out-of-pocket drug expenses.
Federal spending will also drop by an estimated $12 billion across the entire Medicare program. These negotiated discounts directly lower your coinsurance percentage when you fill prescriptions at the pharmacy counter.
“A big part of financial freedom is having your heart and mind free from worry about what-ifs of life.” — Suze Orman, Personal Finance Author
6. Shifting Standalone Part D Plan Premiums
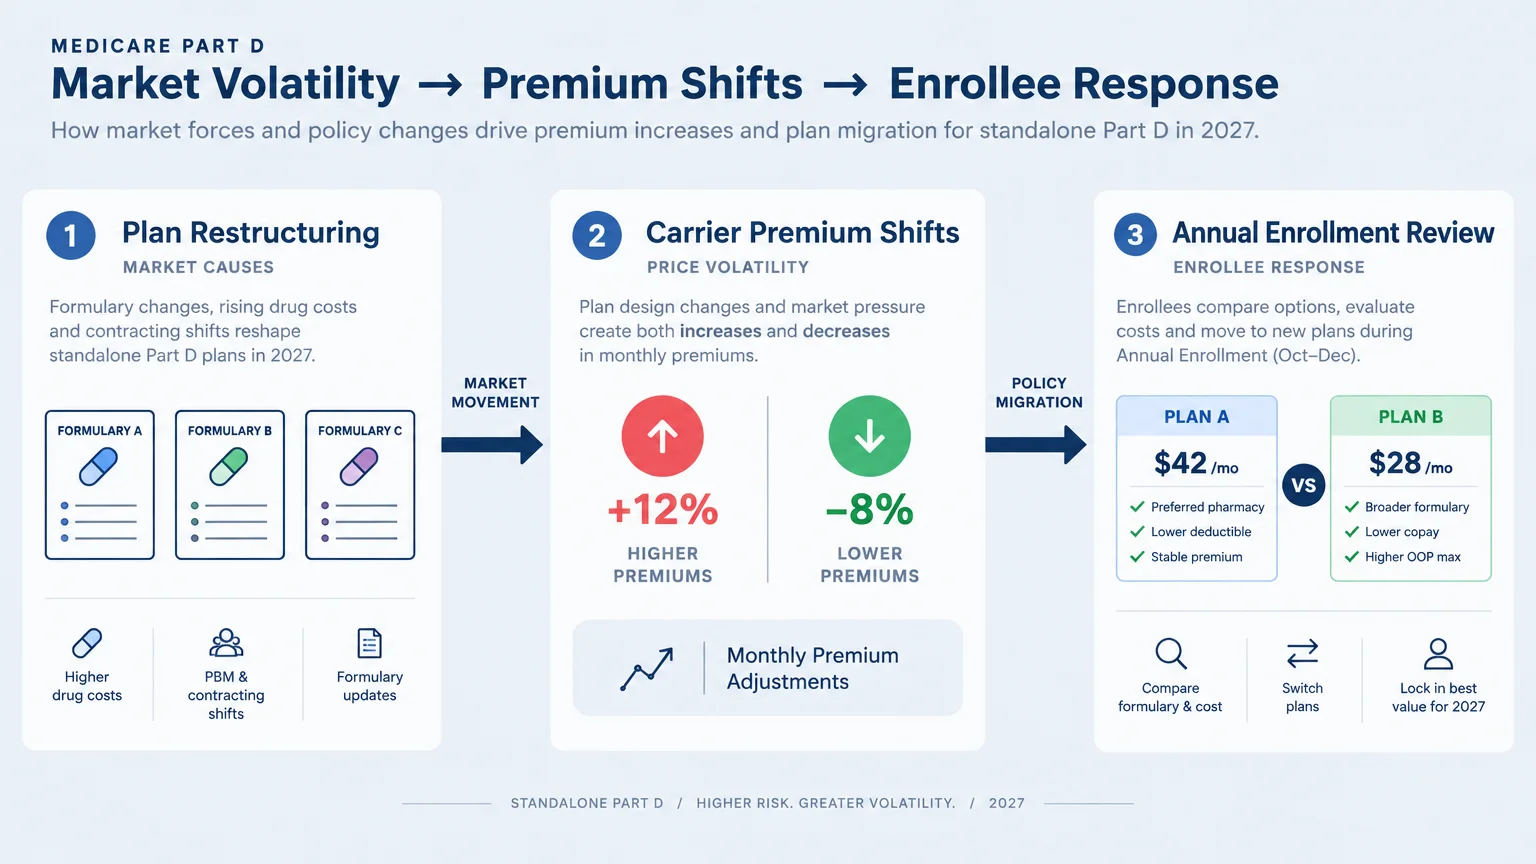
Private drug plans face major pricing adjustments as federal transition programs expire. The temporary Part D Premium Stabilization Demonstration concludes at the end of 2026, ending a roughly $16 monthly federal subsidy.
CMS projects the basic national average premium will hold near $36 per month. However, individual standalone prescription drug plans show marked consolidation, dropping from 367 available plans nationwide to 323.
Without federal subsidies propping up private offerings, higher-tier plans may sharply raise their monthly premiums. Checking your plan’s Annual Notice of Change becomes vital to avoid an unexpected rate shock.
7. Flat-Rate Access Through the GLP-1 Bridge Copay Program
Managing cardiometabolic conditions becomes more predictable thanks to targeted federal protections. Eligible Part D enrollees accessing select GLP-1 medications receive a flat $50 monthly copayment through December 31, 2027.
This bridge program ensures affordable access for individuals using these therapies for cardiovascular risk reduction and diabetes care. It protects your budget while standard formularies integrate broader coverage rules across private health plans.
8. IRMAA Surcharges Tied to Your 2025 Tax Return
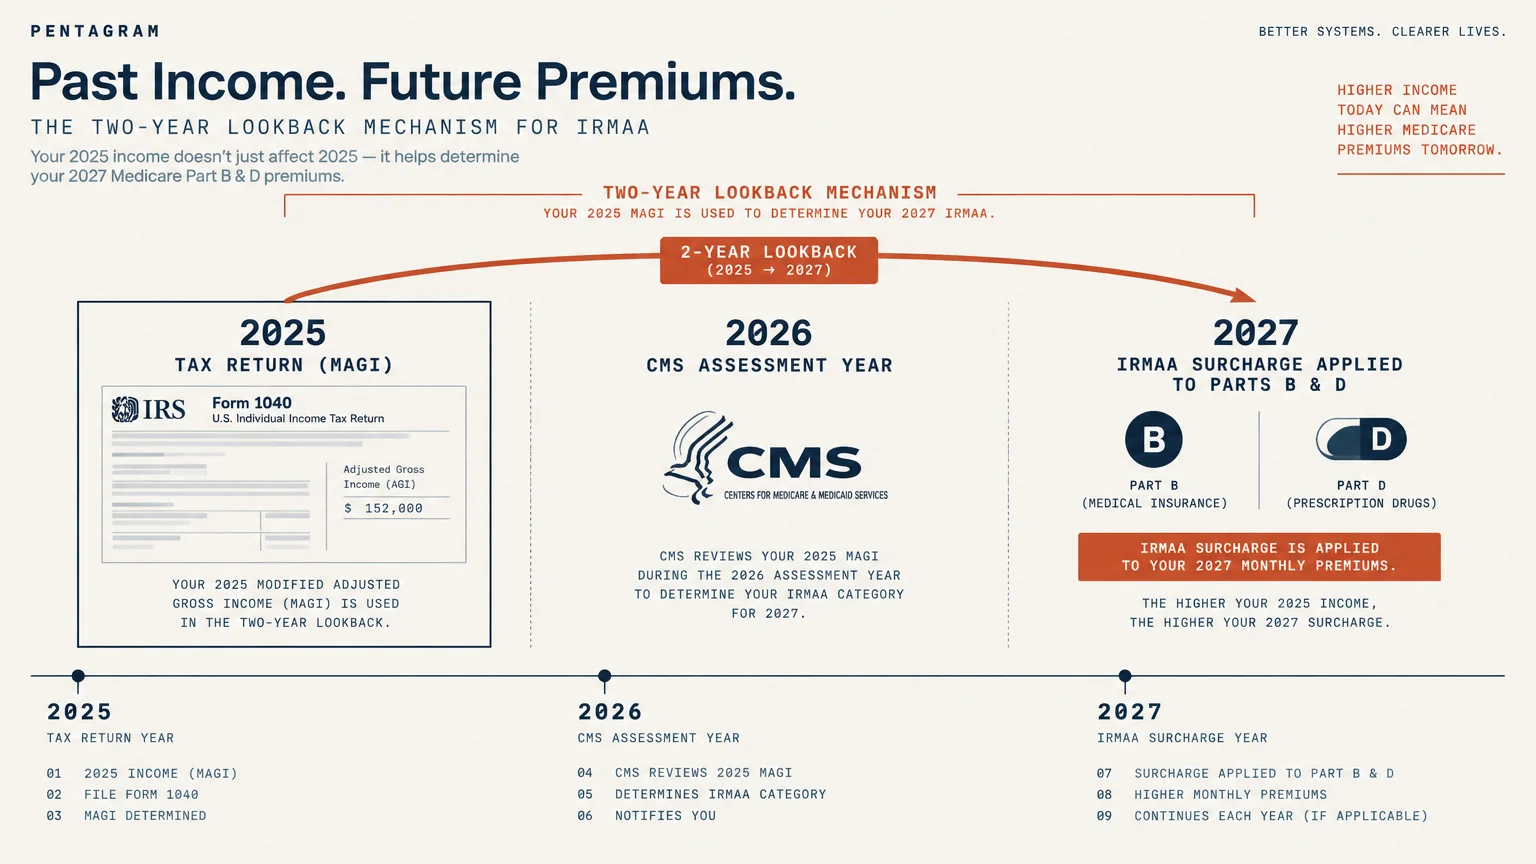
Higher-income retirees face extra monthly fees through the Income-Related Monthly Adjustment Amount (IRMAA). Social Security calculates your 2027 IRMAA tiers using your modified adjusted gross income reported on your 2025 tax return.
These surcharges apply directly to both your Part B outpatient and Part D prescription drug premiums. Even a single dollar over an income tier threshold triggers the higher surcharge bracket for the entire year.
If you experienced a life-changing event in 2026, such as retirement or the loss of a spouse, file Form SSA-44. This official request asks Social Security to recalculate your bracket using current income.
9. Inpatient Hospital Part A Deductibles Per Benefit Period
Most beneficiaries receive Part A hospital coverage premium-free, but inpatient care carries a substantial deductible. This cost applies per benefit period rather than on an annual calendar basis.
A benefit period begins the day you enter the hospital and concludes once you remain discharged for 60 consecutive days. If you experience multiple hospitalizations spaced months apart, you must pay this deductible each time.
For context, the Part A deductible stood at $1,736 in 2026, alongside daily coinsurance of $434 for extended stays. CMS announces the finalized 2027 Part A cost schedule late in the fall.
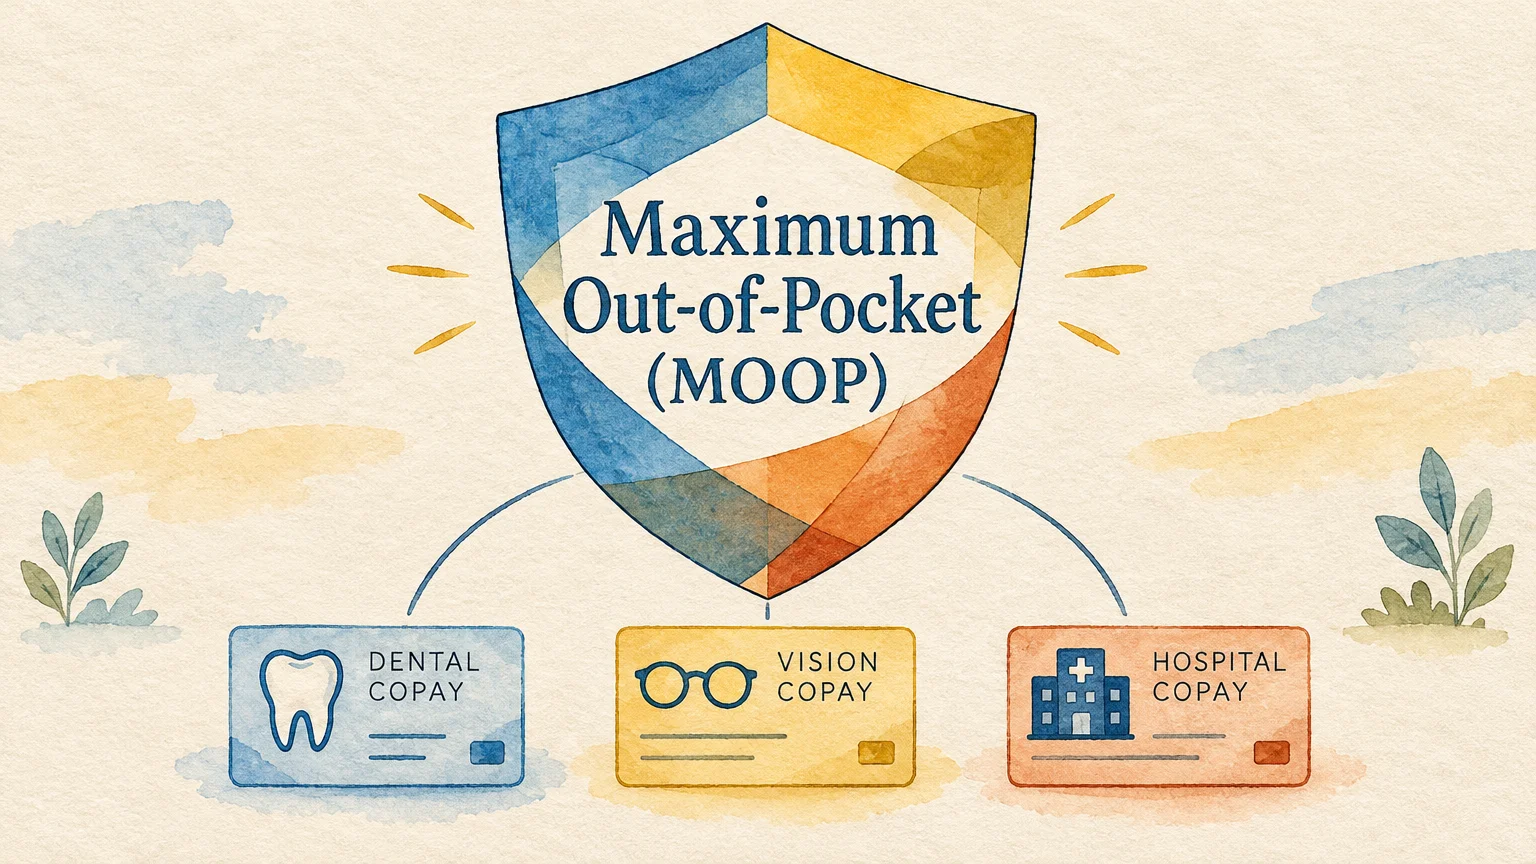
10. Medicare Advantage Maximum Out-of-Pocket Adjustments
If you enroll in Medicare Advantage instead of Original Medicare, pay close attention to your plan’s maximum out-of-pocket (MOOP) limit. Private insurers adjust these caps each year to account for rising medical inflation.
Federal regulations cap in-network MOOP spending, but private plans frequently alter cost-sharing for specialist copays and imaging. You should also watch for reductions in supplemental benefits like dental allowances and grocery stipends.
Avoiding Common Errors During Open Enrollment
Medicare’s annual open enrollment period runs from October 15 through December 7 each year. Taking full advantage of this window protects your wallet against unexpected policy alterations.
- Ignoring the Annual Notice of Change: Review this document every September to check if your doctors, facilities, or maintenance prescriptions face altered tier placement.
- Assuming your current plan remains cheapest: Formularies and monthly premiums shift constantly, meaning last year’s optimal drug plan may become your most expensive option.
- Overlooking pharmacy networks: Preferred pharmacies offer substantially lower copays than standard in-network pharmacies, saving hundreds of dollars over twelve months.
- Missing the IRMAA appeal deadline: Submit your documentation promptly to Social Security if your retirement or income dropped after 2025.
Reviewing these four items before December 7 ensures you keep your overall healthcare spending under control. Compare options directly through the official tools at Medicare.gov.
When DIY Isn’t Enough
Navigating changing healthcare rules can feel overwhelming when your financial or medical circumstances grow complex. Specific situations require personalized guidance from credentialed professionals.
Seek professional assistance if you face any of the following scenarios:
- You trigger sudden IRMAA surcharges: A certified financial planner can coordinate tax-efficient IRA withdrawals to keep your modified gross income beneath costly surcharge cliffs.
- You manage multiple specialty prescriptions: Your local State Health Insurance Assistance Program (SHIP) offers free, unbiased counseling to map complex drug regimens against plan formularies.
- You transition between employer coverage and Medicare: A licensed benefits advisor helps you coordinate Part B enrollment timing without incurring permanent late-enrollment penalties.
- You require long-term financial Medicaid integration: An elder law attorney can protect your household assets while structuring eligibility for state-funded nursing support.
Frequently Asked Questions About Medicare Costs in 2027
What is the projected Medicare Part B premium for 2027?
The Medicare Trustees project the standard Part B premium will rise to $209.50 per month in 2027. CMS publishes the official rate each November.
How does the Part D out-of-pocket cap work in 2027?
Your out-of-pocket costs for covered formulary medications cap at $2,400 for the year. Once you pay this amount, Medicare covers 100% of your drug costs.
Which tax year determines my 2027 Medicare IRMAA surcharge?
Social Security uses your 2025 federal tax return to calculate your 2027 IRMAA tiers. They use a standard two-year lookback to measure modified adjusted gross income.
Can my Social Security benefit decrease if Medicare Part B costs rise?
The hold-harmless provision prevents Part B premium increases from reducing your net Social Security check below the prior year’s payment. This protection covers roughly 70% of beneficiaries.
Taking Control of Your 2027 Healthcare Budget
Staying proactive about these changes gives you total command over your retirement finances. Verify your annual benefits statements every autumn, review drug tier changes, and adjust your personal spending plan accordingly.
Consult official updates directly through the Social Security Administration and Internal Revenue Service to optimize your strategy. You can also read analysis on retirement trends from Kiplinger.
This is educational content based on general financial principles. Individual results vary based on your situation.
Always verify current tax laws, investment rules, and benefit eligibility with official sources.
Last updated: February 2026. Financial regulations and rates change frequently—verify current details with official sources.