You could easily pay hundreds of dollars in unnecessary Medicare Part B premiums each year without realizing it. Automatic deductions vanish straight from your Social Security check before your monthly benefit ever hits your bank account.
Outdated tax returns, administrative billing errors, and missed state subsidies quietly inflate healthcare costs for millions of American retirees. Catching these hidden discrepancies gives you the power to slash expenses and reclaim your hard-earned retirement income.
Use these ten targeted checkpoints to audit your statements, appeal unfair surcharges, and secure your lowest possible Part B rate today.
The Essentials: What Determines Your Medicare Part B Costs
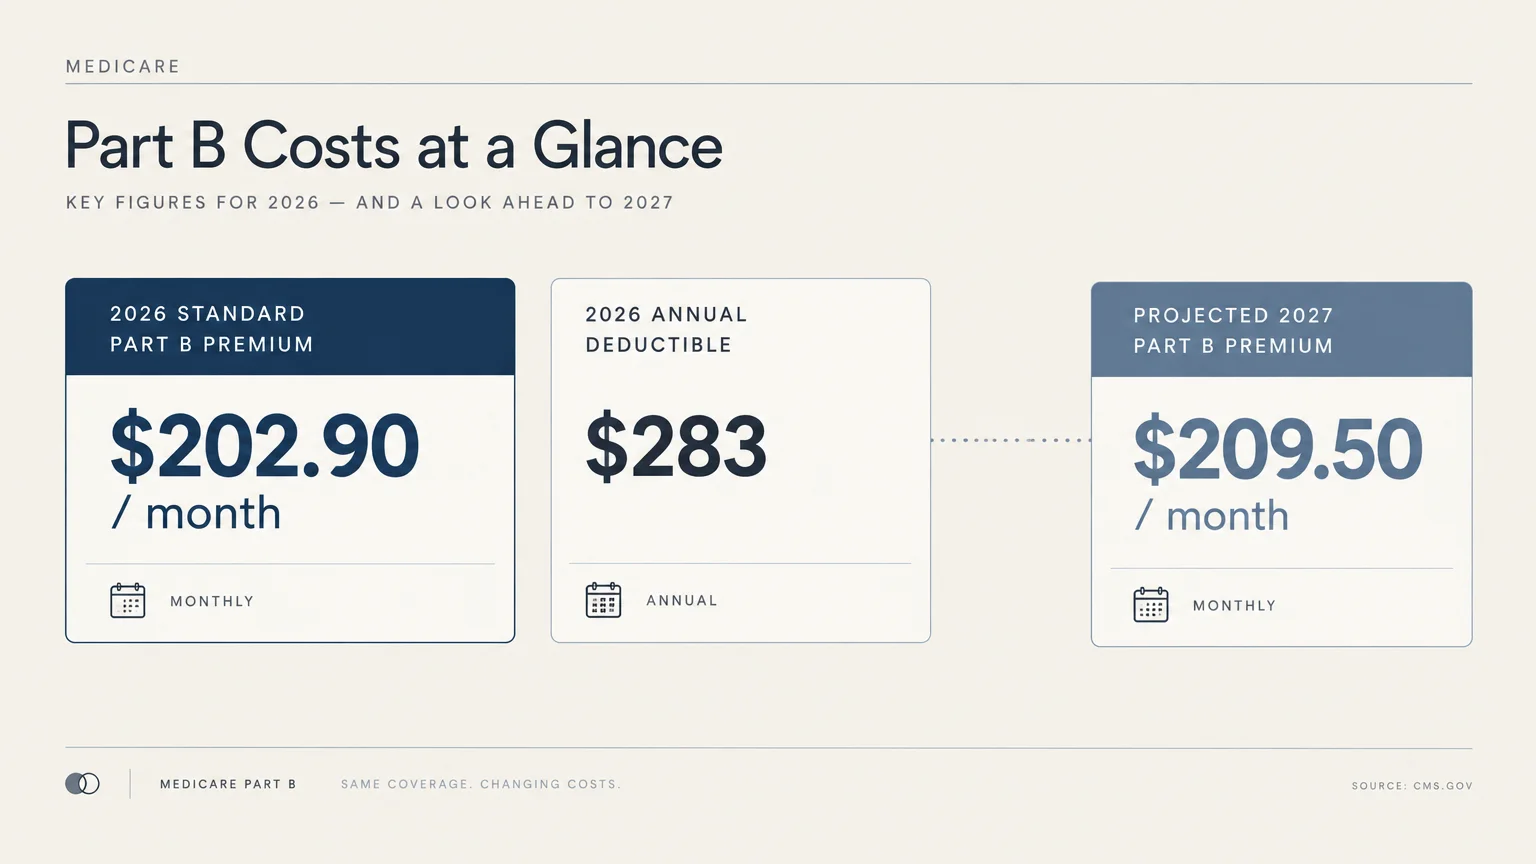
In 2026, the standard Medicare Part B premium is $202.90 per month, alongside an annual deductible of $283.
According to the Medicare Trustees Report, projected medicare part b costs 2027 will reach approximately $209.50 monthly.
While most retirees pay these baseline amounts, hidden surcharges and administrative mistakes can dramatically inflate your expenses.
Knowing how the government calculates your bill ensures you avoid overpaying for Medicare throughout your retirement years.
1. Check for Outdated Tax Data Driving Your IRMAA Surcharge
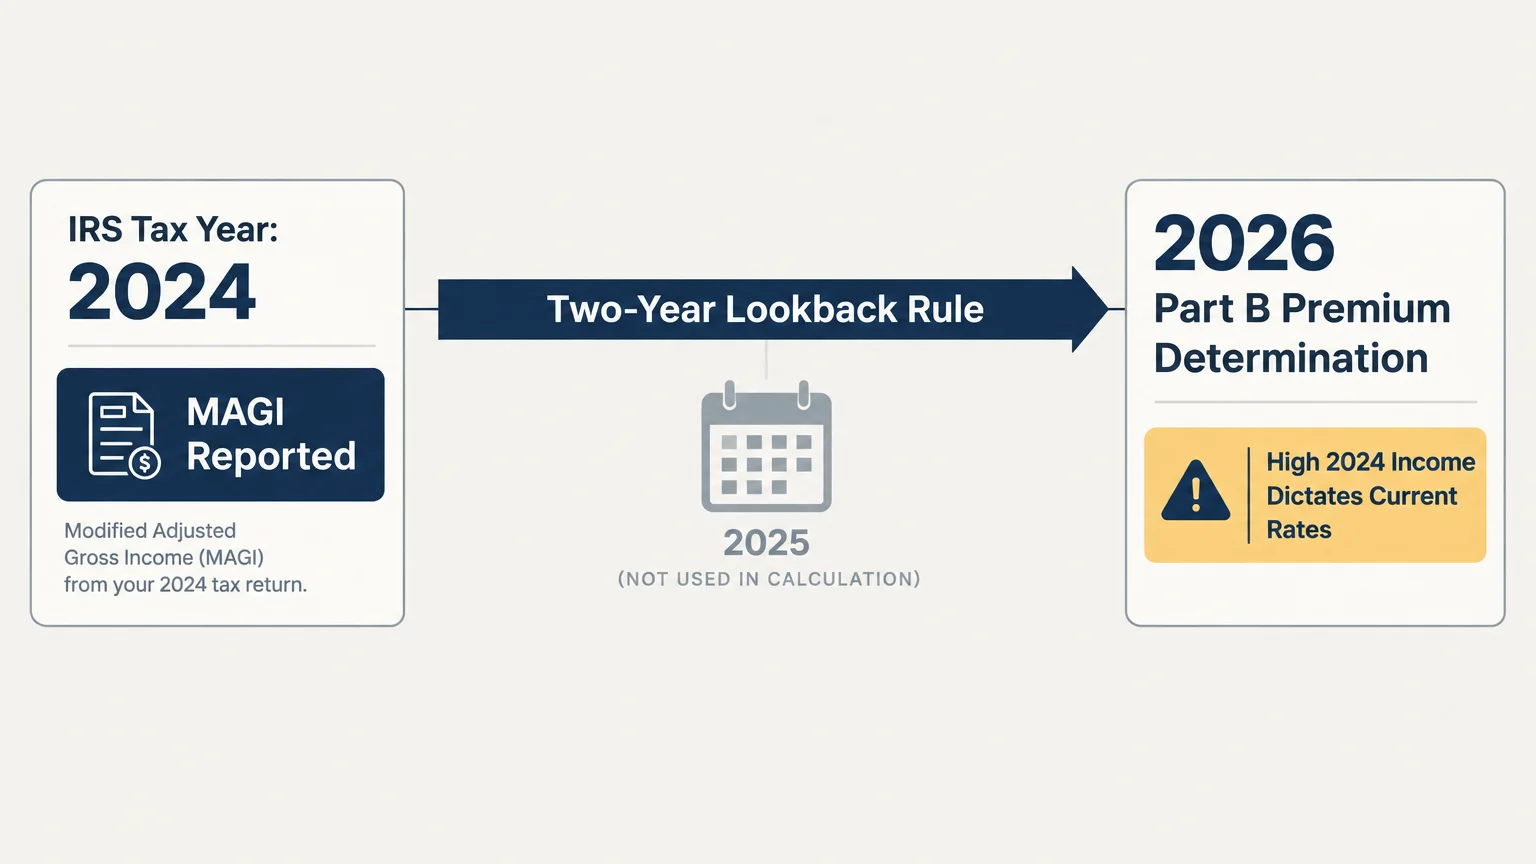
The Social Security Administration calculates your Part B IRMAA using a strict two-year lookback rule.
For your 2026 premium, officials review the Modified Adjusted Gross Income (MAGI) reported on your 2024 tax return from the Internal Revenue Service.
If your income was high two years ago but has since plummeted, Medicare still charges you top-tier rates.
Checking your annual notice against your current cash flow helps you spot this common overpayment trigger immediately.
2. Determine If a Life-Changing Event Qualifies You for Form SSA-44
When an abrupt income reduction occurs, you do not have to endure two years of inflated bills.
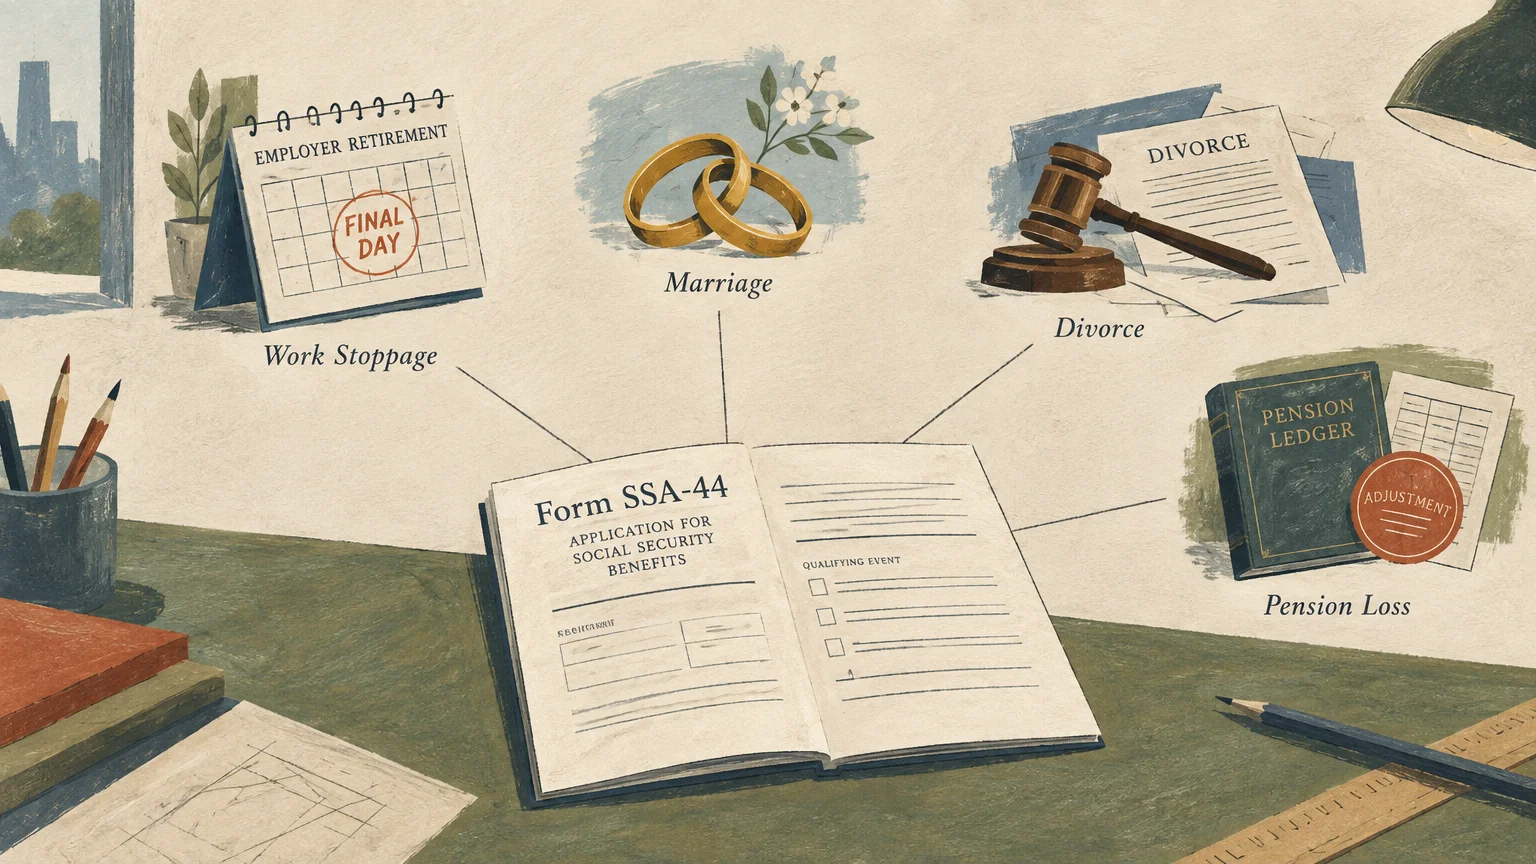
You can file Form SSA-44 with the Social Security Administration to request an immediate rate adjustment.
Federal regulations recognize eight specific life-changing events for an appeal:
- Work stoppage, such as complete retirement
- Work reduction, including shifting from full-time to part-time
- Marriage
- Divorce or legal annulment
- Death of a spouse
- Loss of income-producing property due to a disaster or event beyond your control
- Loss of an employer-sponsored pension plan
- Receipt of a settlement from an employer due to company bankruptcy or closure
Submit proof—such as an employer termination letter or death certificate—alongside your application.
A successful determination recalculates your surcharge using your estimated current-year earnings, providing instant financial relief.
3. Understand the IRMAA Cliff Effect and Review Income Brackets
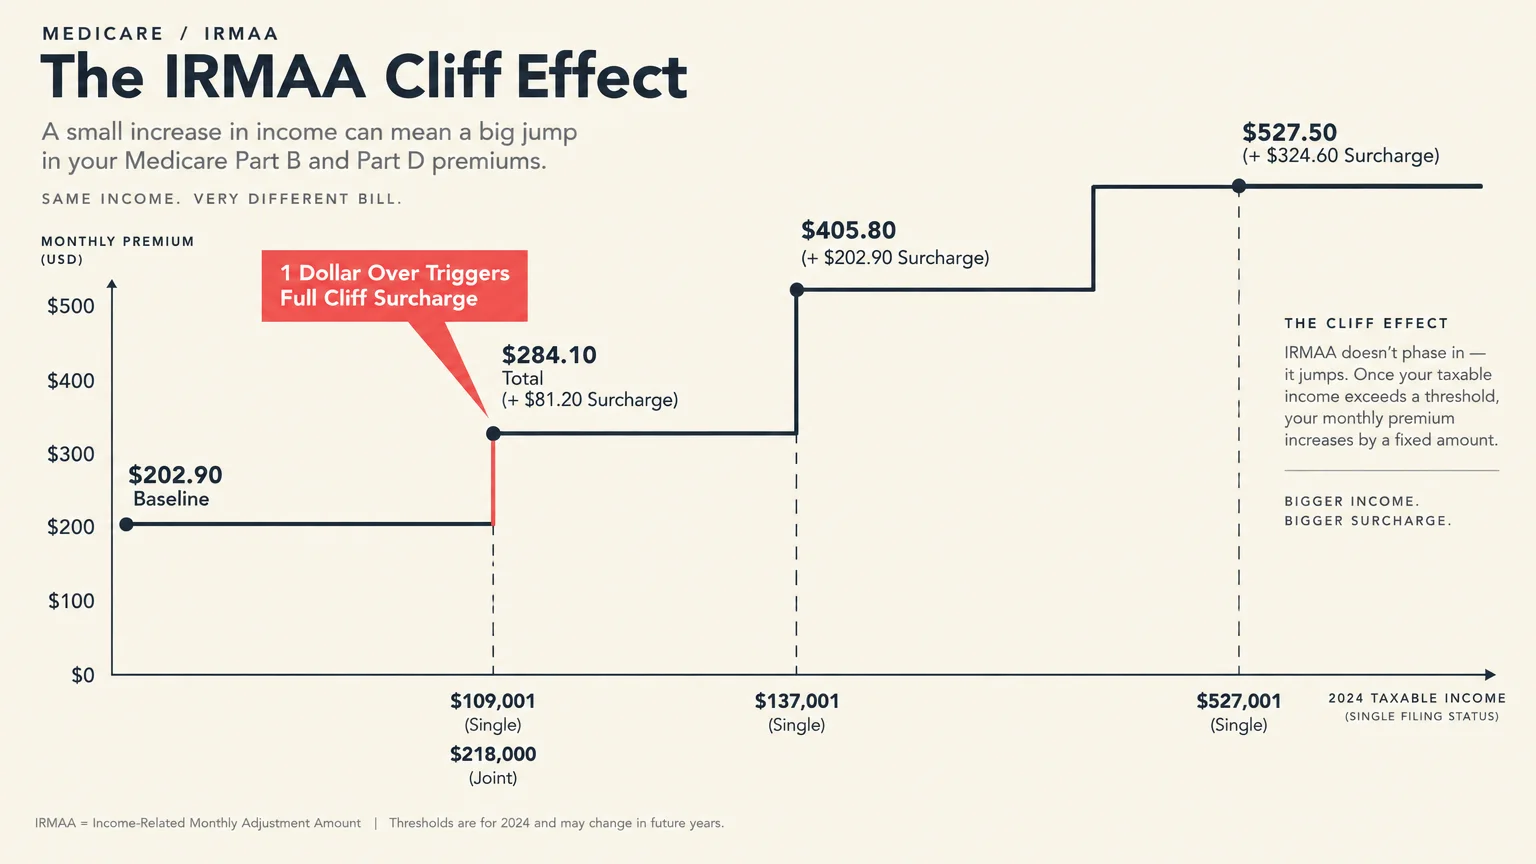
Unlike progressive federal income tax brackets, IRMAA operates as a rigid financial cliff.
Earning just one single dollar over a bracket limit locks you into the full surcharge tier for an entire year.
For 2026, single filers earning more than $109,000 and married joint filers exceeding $218,000 face immediate surcharges.
| 2024 Taxable Income (Single) | 2024 Taxable Income (Married Joint) | 2026 Monthly Part B IRMAA Surcharge | Total 2026 Monthly Premium |
|---|---|---|---|
| $109,000 or less | $218,000 or less | $0.00 | $202.90 |
| $109,001 – $137,000 | $218,001 – $274,000 | +$81.20 | $284.10 |
| $137,001 – $171,000 | $274,001 – $342,000 | +$202.90 | $405.80 |
| $171,001 – $205,000 | $342,001 – $410,000 | +$324.60 | $527.50 |
| $205,001 – $499,999 | $410,001 – $749,999 | +$446.40 | $649.30 |
| $500,000 or more | $750,000 or more | +$487.00 | $689.90 |
Review line 11 on IRS Form 1040 plus your tax-exempt interest to check your standing.
Careful income timing near these sharp cutoffs can lower Medicare premiums by hundreds of dollars each month.
4. Audit Your Premium for an Incorrect Late Enrollment Penalty
Failing to enroll in Part B when you first become eligible can trigger an expensive late enrollment penalty.
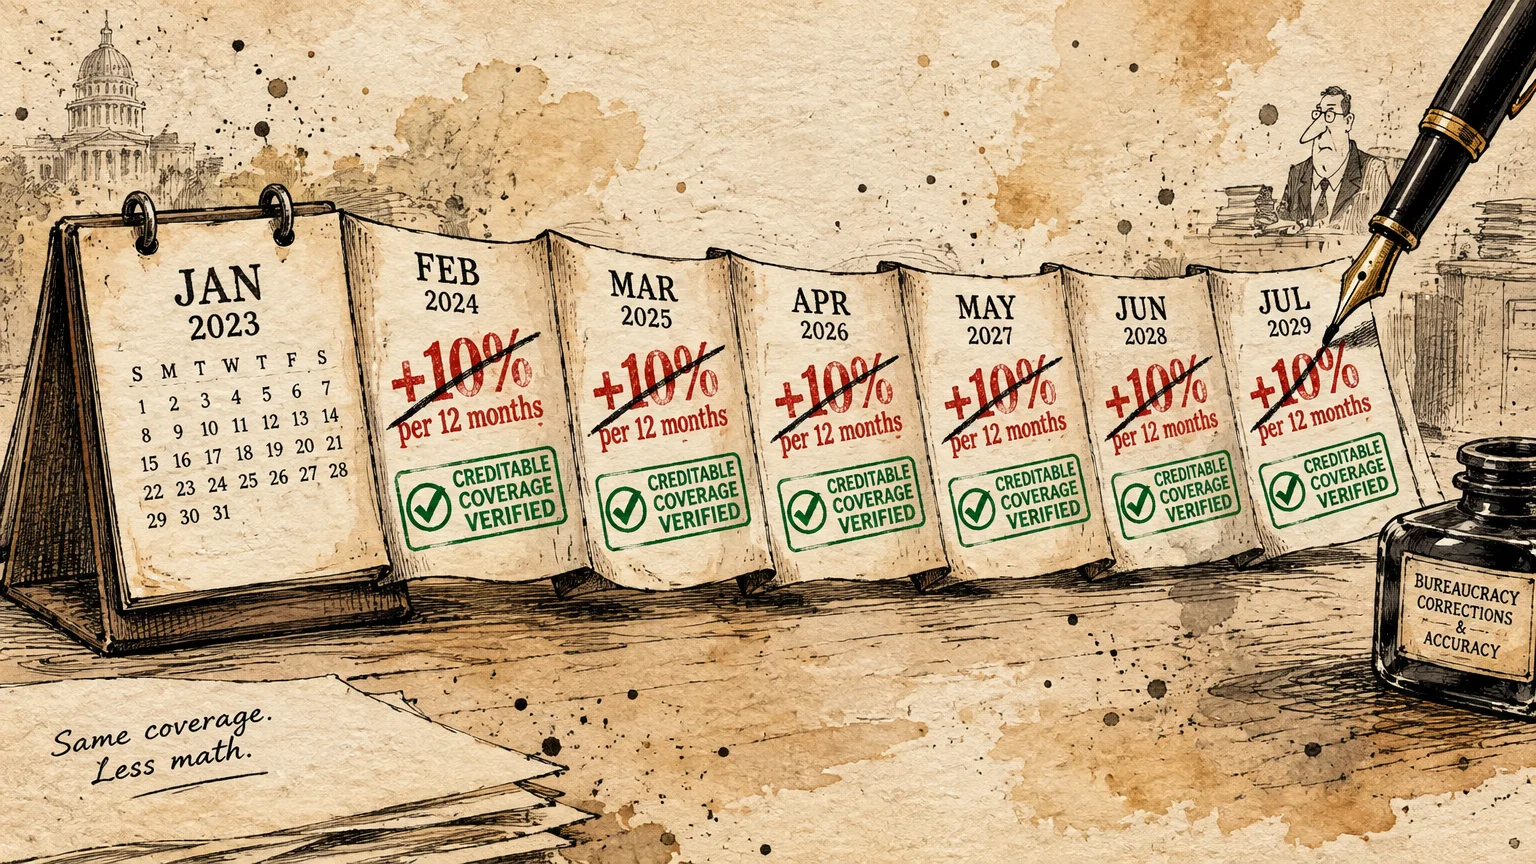
The federal government adds a permanent 10% surcharge for every full 12-month period you went without qualifying coverage.
Because this lifetime penalty compounds with each annual baseline rate hike, clerical errors can cost you thousands over time.
Inspect your monthly Medicare statement to verify whether the agency is mistakenly tacking a penalty onto your bill.
5. Verify Past Employer Coverage Under Creditable Coverage Rules
You can safely delay Part B only if you have qualifying coverage through an active Employer Group Health Plan.
To meet federal guidelines, that employer must have 20 or more active employees.
Many retirees mistakenly believe that COBRA coverage or retiree health benefits count as creditable coverage.
Neither COBRA nor retiree plans qualify under federal law, leaving you exposed to retroactive lifetime surcharges.
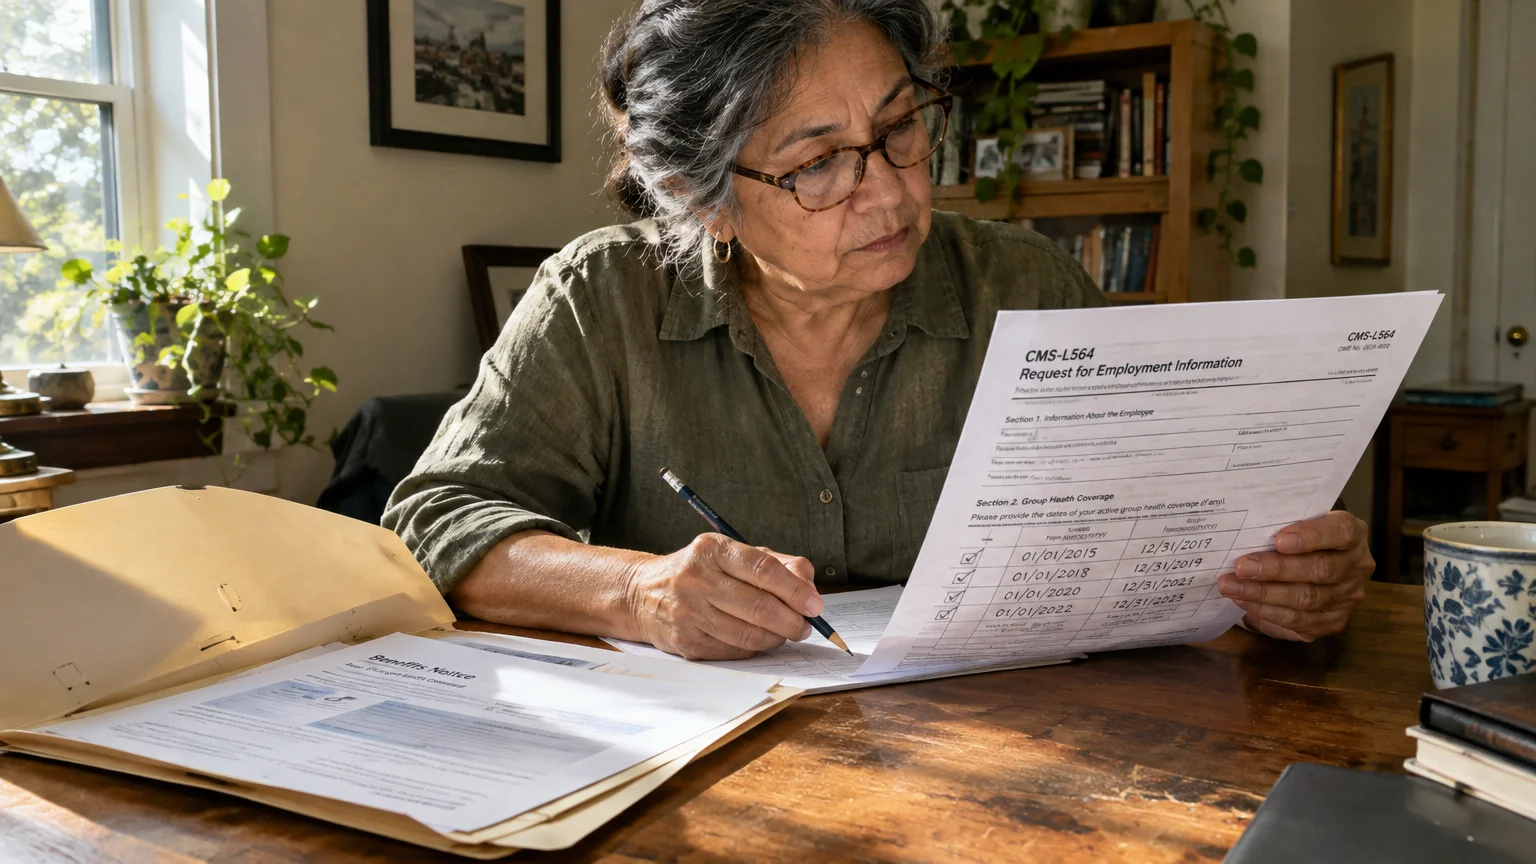
Submit Form CMS-L564 completed by your past benefits administrator to prove continuous active coverage and correct billing penalties.
6. Screen for Medicare Savings Programs to Eliminate Premiums
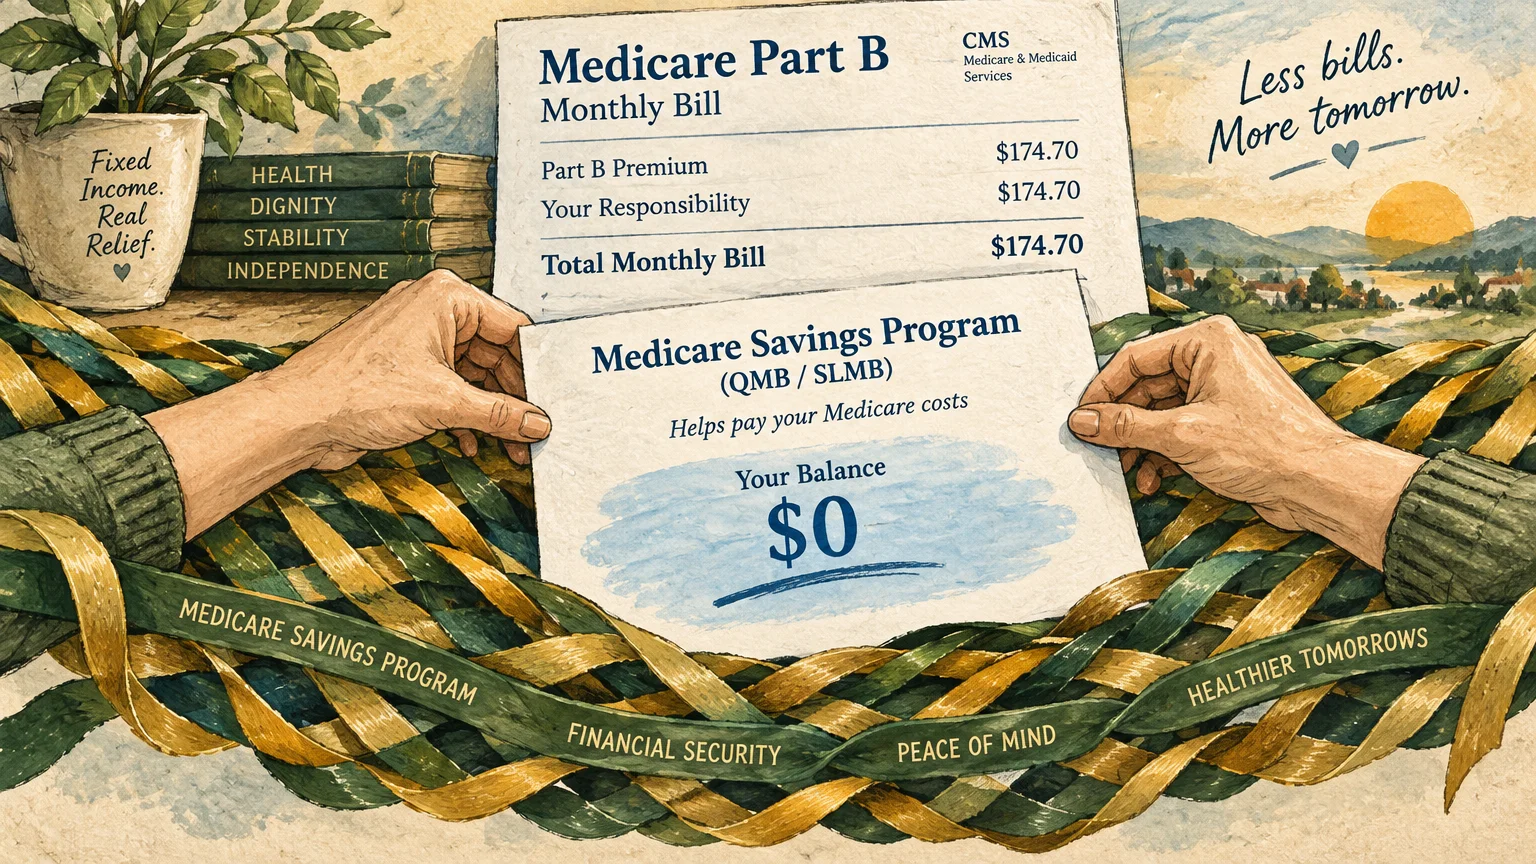
State-funded Medicare Savings Programs (MSPs) offer full premium coverage for eligible individuals with lower incomes.
The Qualified Medicare Beneficiary (QMB) program pays your full Part B monthly premium along with deductibles and coinsurance.
In 2026, baseline income limits are roughly $1,350 monthly for individuals and $1,824 for married couples.
Other programs—like SLMB and QI—eliminate your monthly premium if your income falls within 120% to 135% of poverty guidelines.
Several states enforce significantly higher thresholds or waive resource tests completely, so apply even if you suspect you exceed caps.
7. Evaluate Medicare Advantage Giveback Rebates
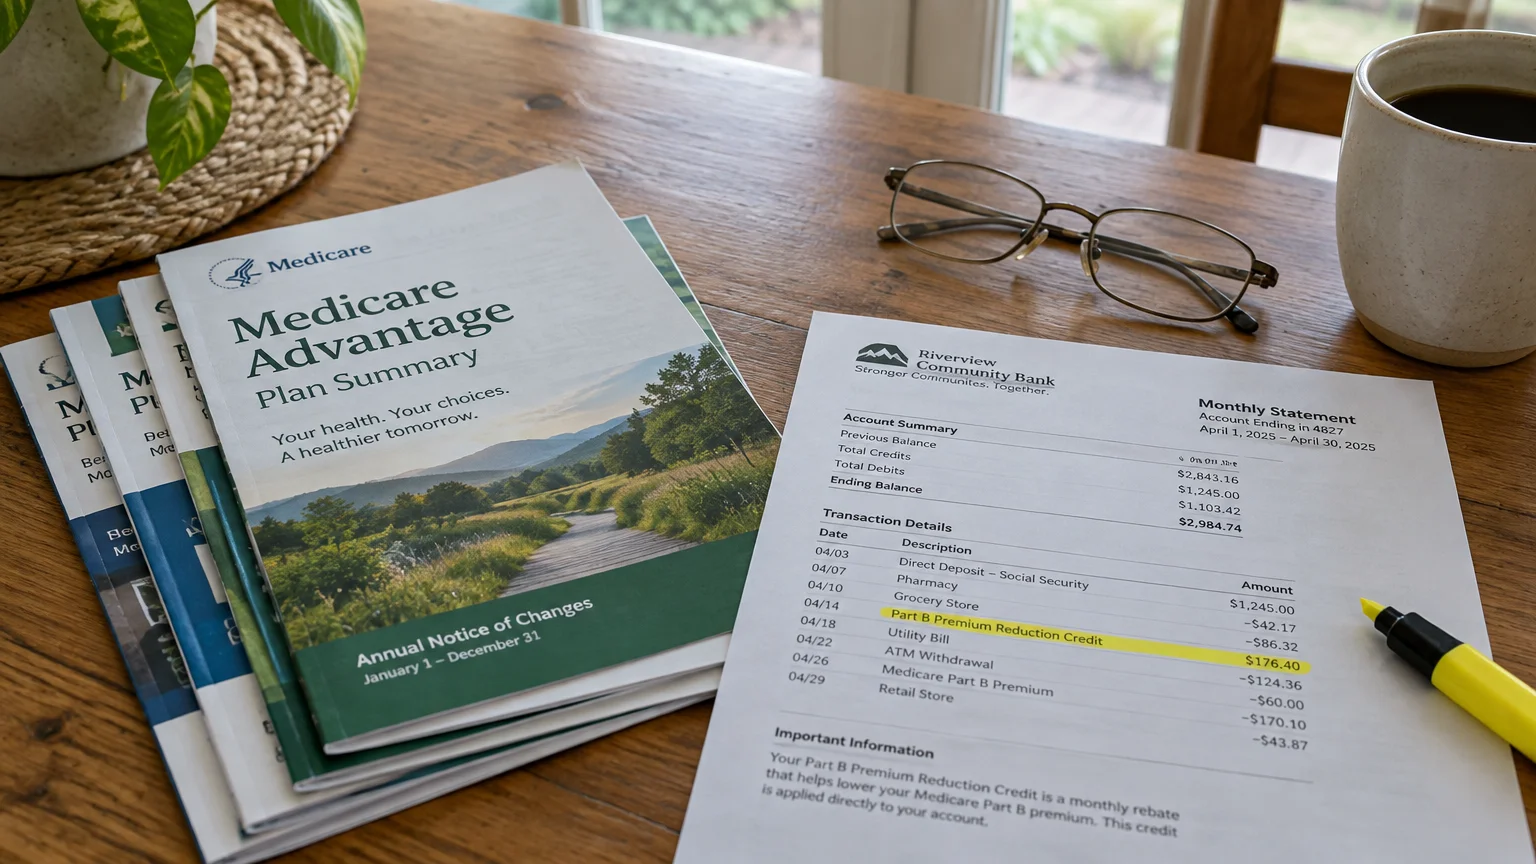
Certain Medicare Advantage plans feature a Part B premium reduction benefit known colloquially as a giveback.
Under this design, the private insurance carrier pays a portion of your monthly premium on your behalf.
That rebate—often ranging between $10 and $100 per month—is credited directly back to your Social Security check.
You can compare regional giveback options using the official plan finder on Medicare.gov.
Always verify provider networks and drug formularies before enrolling, ensuring premium savings do not cause higher treatment copays.
8. Check If the Hold Harmless Provision Protects Your Rate
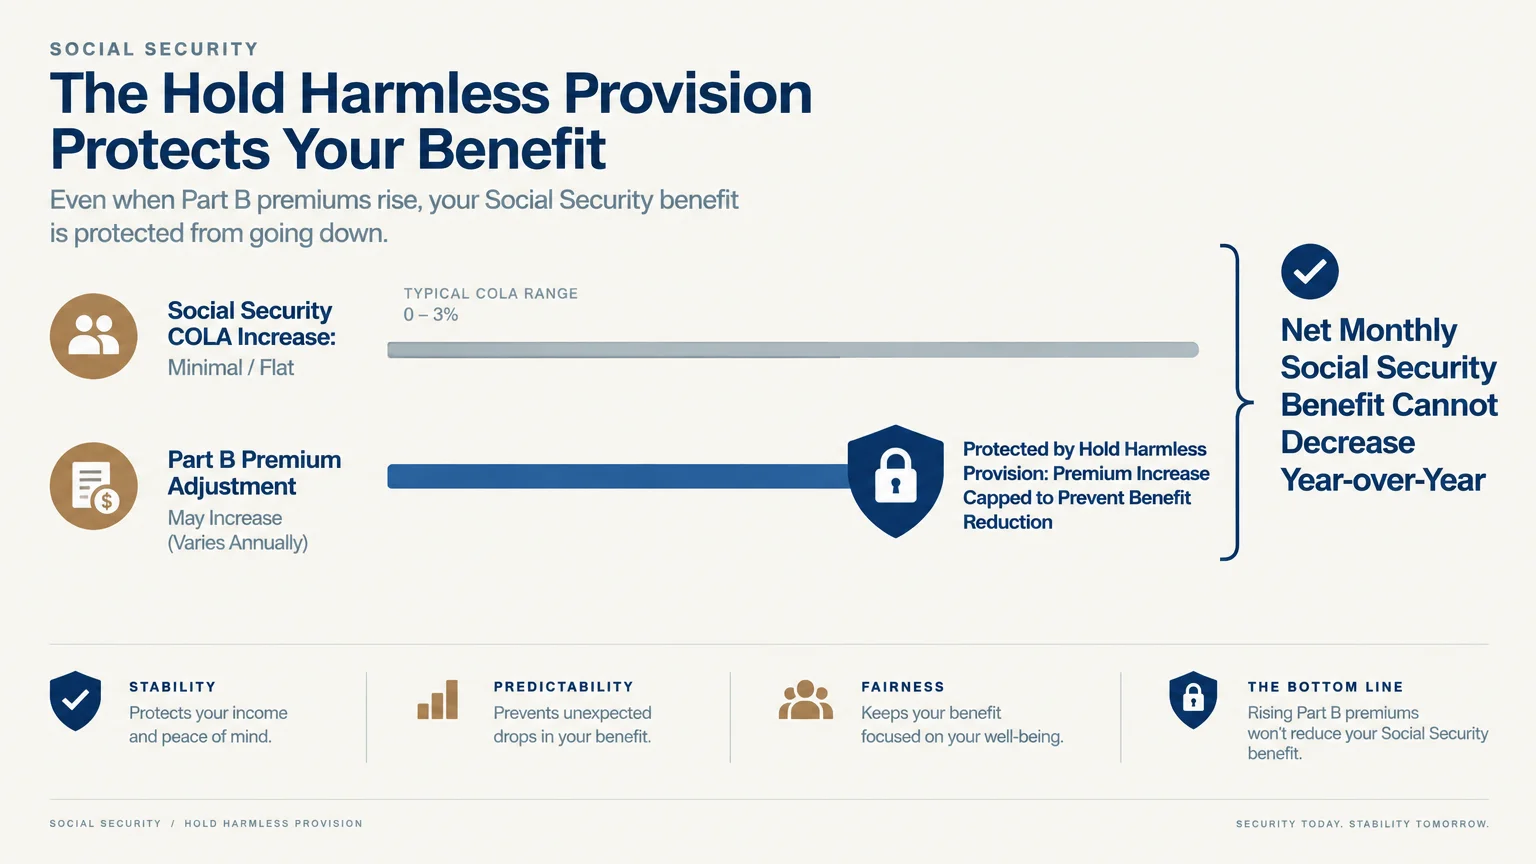
The federal Hold Harmless provision under Section 1839(f) of the Social Security Act safeguards your monthly income.
This law dictates that standard Part B premium hikes cannot exceed your annual Social Security Cost-of-Living Adjustment.
The restriction prevents your net Social Security benefit check from decreasing from one year to the next.
However, this protection excludes high earners paying IRMAA surcharges and individuals paying premiums directly by check.
Confirm whether you are shielded under this rule if a premium increase outpaces your net monthly benefit adjustment.
“Look at where your money is going, because small leaks sink great ships.” — Suze Orman, Personal Finance Author
9. Identify One-Time Income Spikes That Cause Temporary Overpayments
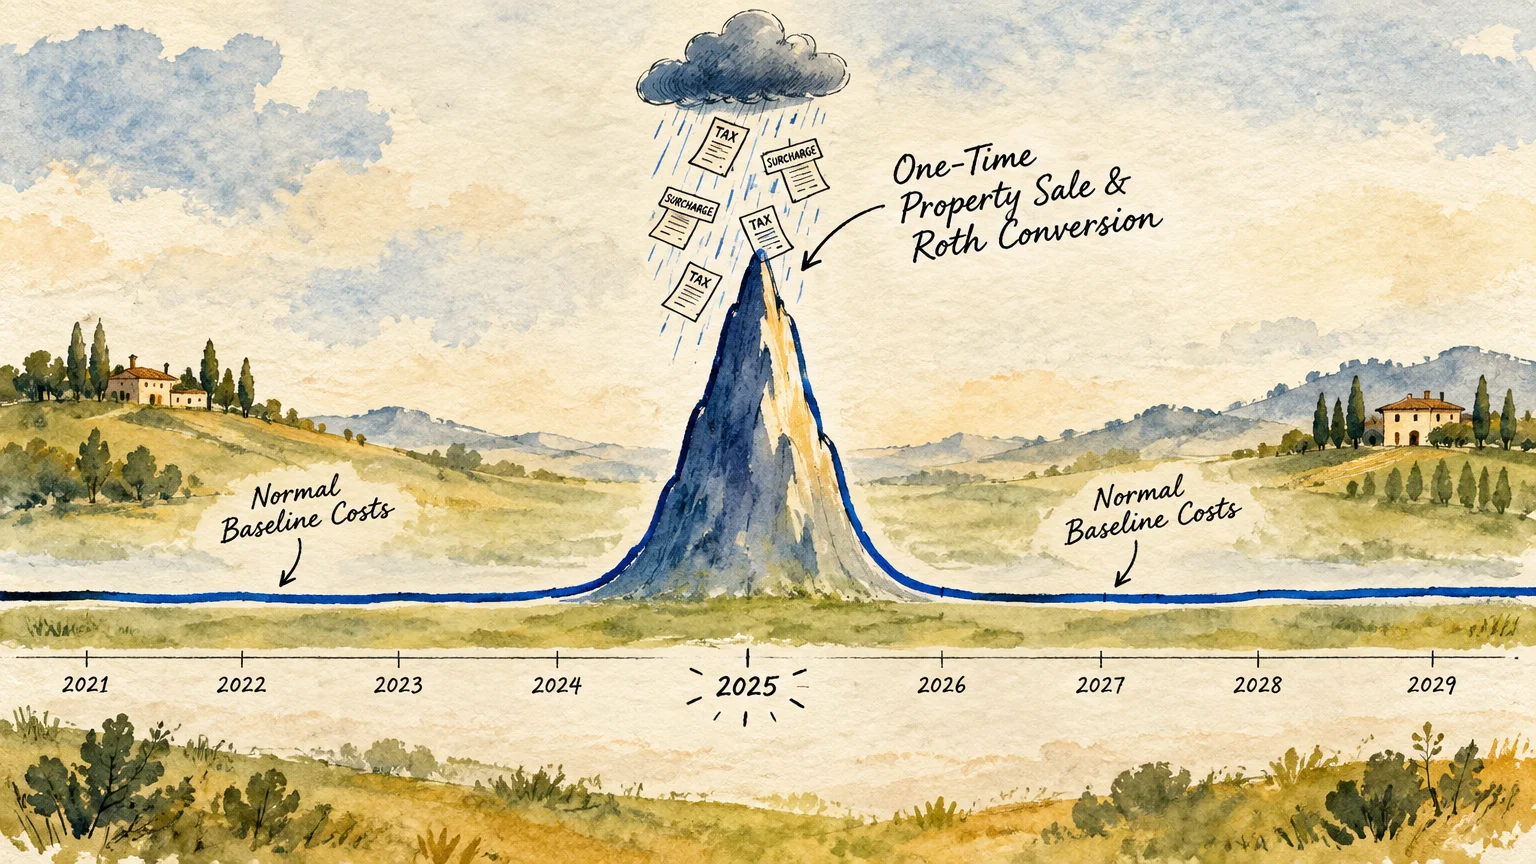
An isolated financial event can trigger unexpected Part B IRMAA penalties two years later.
Selling real estate, taking massive retirement account distributions, or executing large Roth IRA conversions all push up your MAGI.
Unfortunately, the Social Security Administration does not classify voluntary capital transactions or Roth conversions as appealable life events.
You must absorb the higher surcharge for that specific calendar year until the lookback cycle rolls forward.
Staging Roth conversions across multiple tax years helps keep your annual income beneath strict IRMAA cliffs.
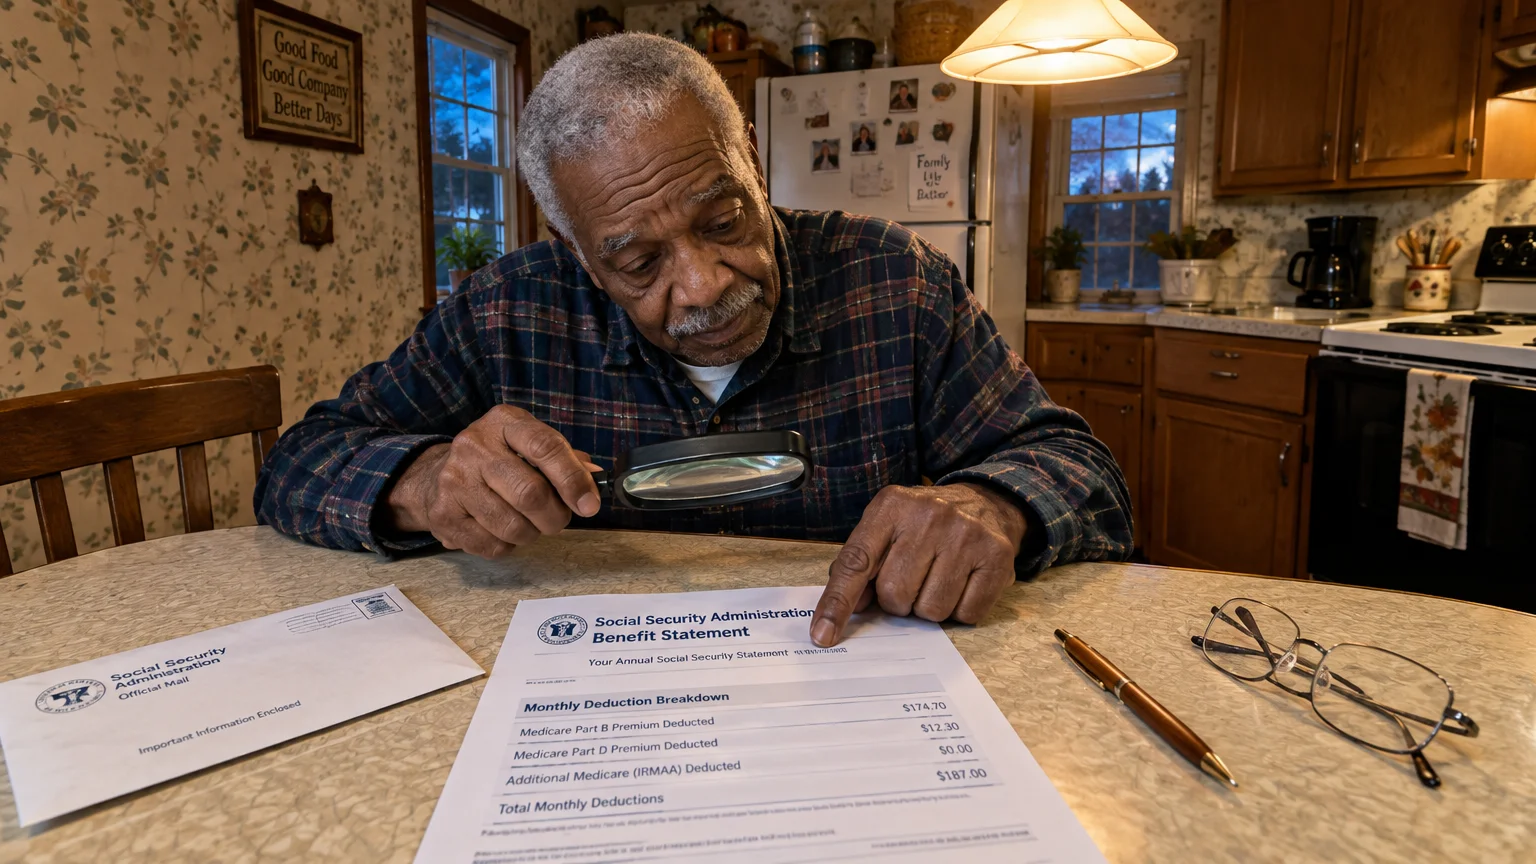
10. Audit Your Social Security Deduction Statements for Billing Glitches
Relying on automatic deductions makes it remarkably easy to overlook small, recurring billing errors.
Government databases sometimes process life events tardily or continue applying penalties after an appeal is formally granted.
Sign into your online my Social Security profile periodically to inspect your itemized deduction lines.
Compare the deduction against the current $202.90 standard rate and your verified IRMAA category.
Contact your local Social Security field office immediately if an unauthorized surcharge appears on your statement.
What Can Go Wrong When Disputing Medicare Costs
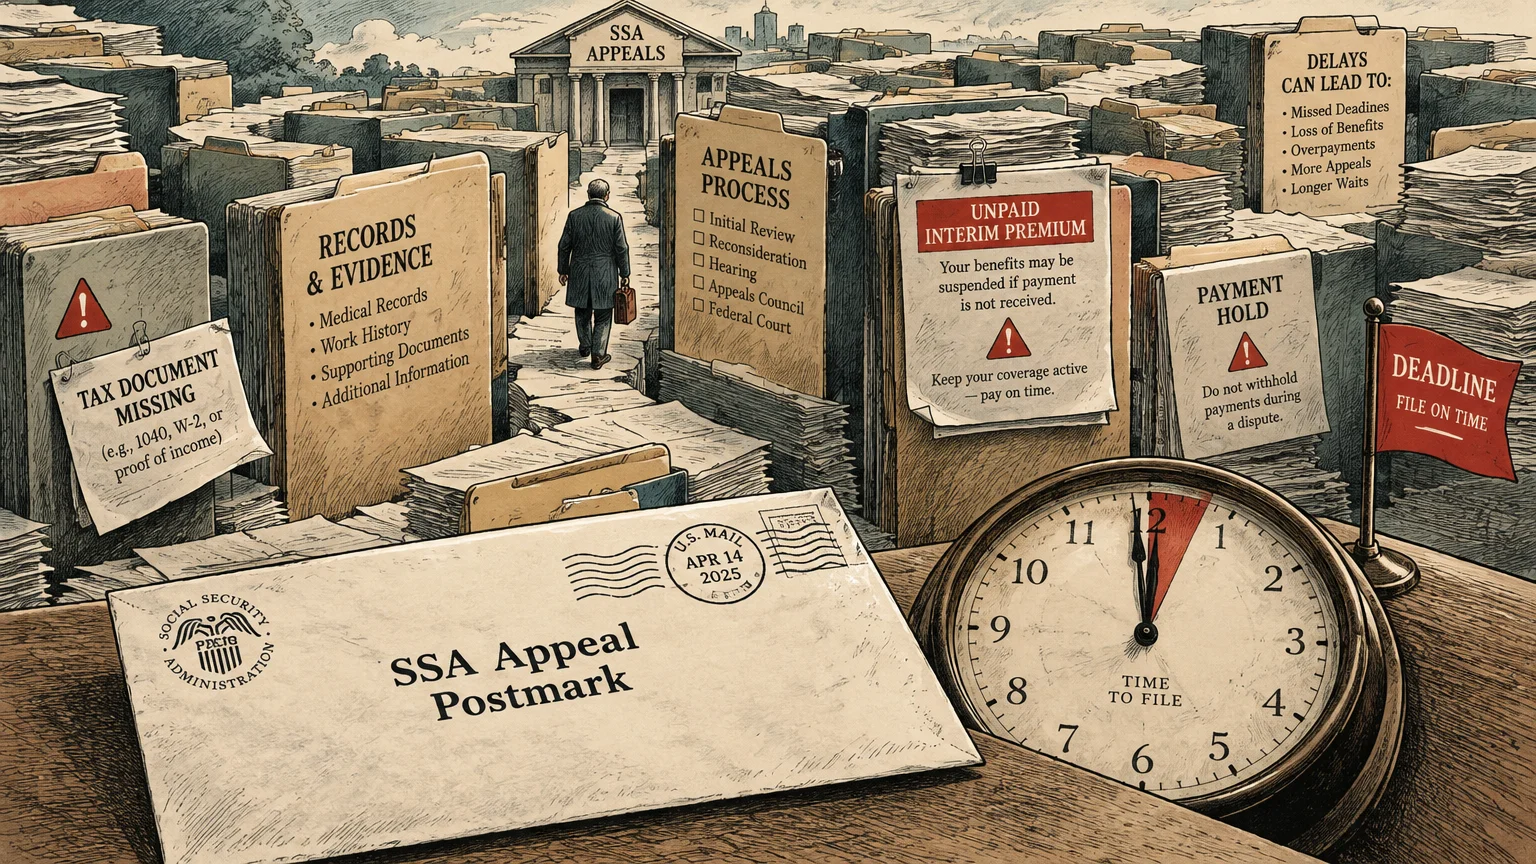
Submitting Form SSA-44 without certified supporting documents will stall your case in administrative limbo for months.
Refusing to pay a disputed surcharge while waiting for an appeal decision can lead Medicare to cancel your outpatient coverage.
Assuming that COBRA qualifies as creditable coverage creates permanent penalties that administrative appeals cannot legally reverse.
Always submit appeal paperwork via certified mail or visit an office in person to obtain a date-stamped receipt.
When to Consult a Professional
You are planning large investment sales or Roth conversions that risk pushing you past steep IRMAA cliffs.
The Social Security Administration denied your Form SSA-44 appeal despite documented evidence of a qualifying life event.
You need help evaluating complex state Medicaid asset rules to qualify for a Medicare Savings Program.
Consulting a fee-only financial planner or a local State Health Insurance Assistance Program (SHIP) volunteer provides unbiased guidance.
Frequently Asked Questions
Can I receive a refund if I overpaid my Part B premium?
Yes, Social Security issues direct retroactive refunds or credits future monthly benefit checks once an error is rectified.
How long does Social Security take to process Form SSA-44?
Processing typically takes 60 to 90 days depending on local staffing and documentation completeness.
Keep paying your invoiced amounts during review to prevent any lapse in outpatient healthcare coverage.
What are the projected Medicare Part B costs for 2027?
According to the Medicare Trustees Report, the standard monthly premium is projected to reach $209.50 with a $292 annual deductible.
Official 2027 figures are published by CMS in late fall of the preceding year.
Does selling a primary home qualify as an IRMAA life-changing event?
No, capital gains from selling real estate do not qualify under the eight approved life-changing event categories.
You must pay the resulting surcharge for that single year until tax records roll forward.
Taking Action on Your Medicare Part B Costs
Regular audits of your Medicare statements take minimal time and protect your retirement nest egg from needless drain.
Check your income brackets, verify creditable coverage records, and challenge inaccurate surcharges to secure your correct premium.
The information in this guide is meant for educational purposes. Your specific circumstances—including income, debt, tax situation, and goals—may require different approaches. When in doubt, consult a licensed professional.
Last updated: February 2026. Financial regulations and rates change frequently—verify current details with official sources.